Fixed Fee, Variable Term and Variable Repayment Product
1. Why can’t we calculate APR for this loan?
APR cannot be calculated for our MCA product as it has a variable term, and various features of repayment methods, such as open-ended instalments and varied amount payable in each instalment. You repay your loan with a fixed % of your revenue, so on days your business does well, we collect more; and on days when your business volume is lower, we collect less. You will never pay more than was agreed at the outset — we only charge a fixed fee, and there are no other hidden fees.
2. How does our repayment differ from a conventional loan?
Our MCA loans offer flexible and variable repayments based on your daily sales, while conventional loans have fixed repayments on set dates. With our MCA loan, we provide a stress-free financing journey by tying your repayments to your cash flow – on days your business does well, we collect more; and on days when your business volume is lower, we collect less. The better your business performs, the faster your loan to us will be repaid.
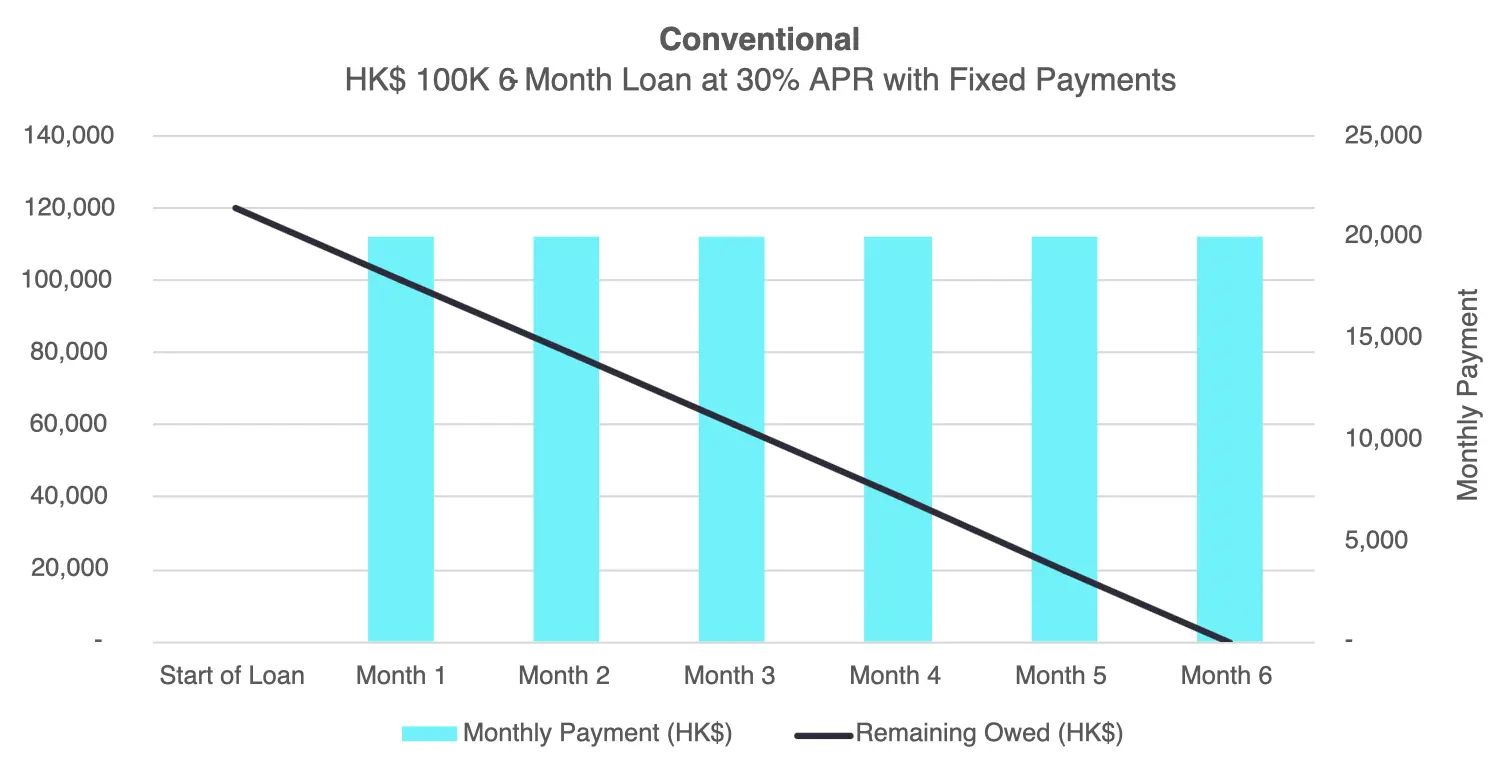
If you took a conventional 6-month loan at an APR of 30% (i.e. not our MCA loan), you would have a monthly payment schedule as shown in Graph 1.
With a Fixed Fee and Variable Repayment Loan, your repayments will change each month based on how your business performs — as shown in Graph 2. Because the repayment amount varies, we can’t show an exact APR. The total amount you’ll repay doesn’t change though — it’s simply the Loan plus the Loan Fee.
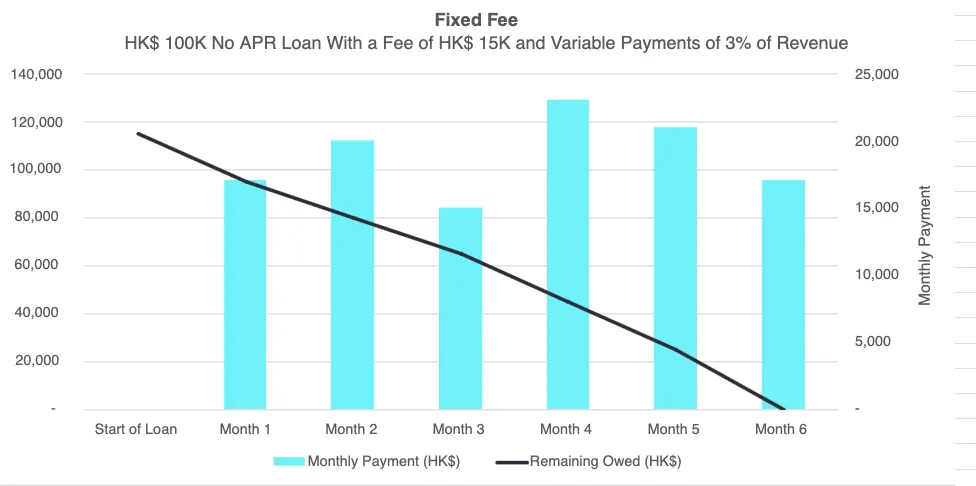
In both cases you will pay off the loan, but with a Fixed Fee, Variable Term, Variable Repayment loan, you do not face an end of the month payment that may be onerous if your business has a slow month – payments adjust to your commercial reality.
We show an estimated APR based on the assumption that you make equal daily payments over the full loan term. This is just a guide — it’s not a true APR. Fee-Based Variable Repayment Loans don’t have a fixed APR, but you’ll only ever repay the Loan Amount plus the Fee — no more, no less.
Regardless of how much you pay every day, you will NEVER pay us more than the principal and the fee. That’s our transparent commitment to you.
3. How do I pay off the loan?
All businesses have good revenue days and bad revenue days, and we have tailored our product to assist with this reality by charging a “sales withholding rate” which is a percentage of the revenue that flows through your account with our partner. We withhold this percentage from you, which then goes towards paying off the loan and fee.
Your sales withholding rate is a % of your revenue, so on days your business does well, we collect more; and on days when your business volume is lower, we collect less. In this way we partner with you for both the good and the not so good times. Graph 3 shows what monthly repayments would be made on a business that had a 3% sales withholding rate.
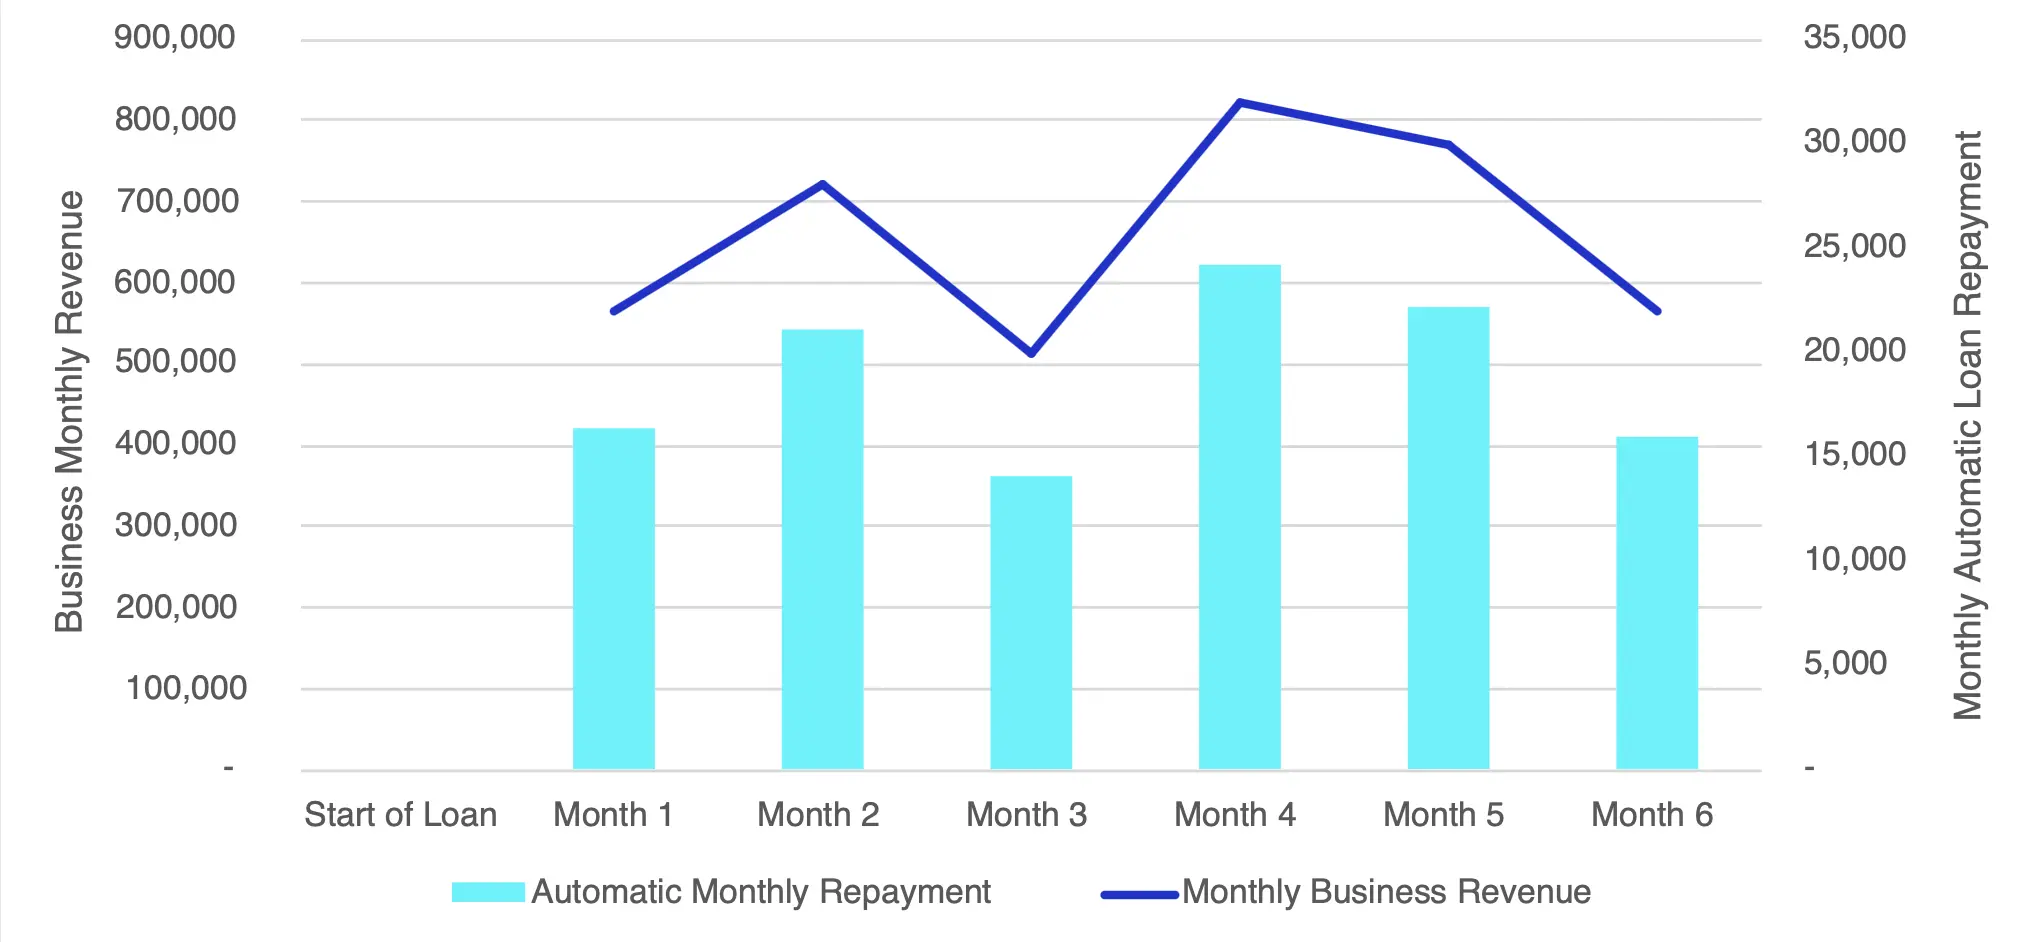
Even though your repayments to us are variable, we expect to be repaid in full eventually and provide an estimated payment period for your loan. We know that sometimes you may pay off the loan and fee early. Regardless of the changes in your revenues, you have to repay the full amount of the loan (the principal and the fee) in full. You have a contractual obligation to continue using our partner’s platform as you have historically done so, when you take out this loan.
You will never pay back more than the original loan amount plus the one-time fee. Once your repayments reach that total, no further deductions will be made from your revenue.